
Lessons in this course
- 1What Is Fundamental Analysis
- 2Reading the Income Statement
- 3Reading the Balance Sheet
- 4Reading the Cash Flow Statement
- 5Common SEC Filings and What They Tell You
- 6Valuation Basics: P/E, P/S, and EV/EBITDA (current lesson)
- 7Economic Moats and Competitive Position
- 8Catalysts, Dilution Risk, and Red Flags
- 9Return on Equity and Leverage
Valuation Basics: P/E, P/S, and EV/EBITDA
Produced with AI assistance. Reviewed by QuietTicker Editorial.
Valuation multiples compress a company's financials into a single ratio that can be compared against peers and against the company's own history. No multiple is a complete answer on its own — each one answers a slightly different question, and each one can mislead when used without context.
Price-to-Earnings (P/E)
The P/E ratio divides a company's share price by its earnings per share, expressing how many dollars investors are paying for each dollar of annual profit. A high P/E can mean a stock is expensive, or it can mean the market expects earnings to grow substantially in the future — a fast-growing company can trade at a high P/E and still be reasonably priced relative to where its earnings are headed, while a mature company at the same P/E might genuinely be overpriced. P/E is undefined (or not meaningful) for unprofitable companies, which is the first limitation worth knowing.
Price-to-Sales (P/S)
Price-to-sales divides market capitalization by revenue, and its main advantage over P/E is that it works for companies that aren't yet profitable, which makes it the more common multiple for early-stage growth companies. Its weakness is the mirror of that strength: revenue says nothing about whether a company can ever convert that revenue into profit, so a low P/S on an unprofitable company isn't automatically a bargain.
EV/EBITDA
Enterprise value (EV) is market capitalization plus debt minus cash — a more complete measure of what it would actually cost to acquire the whole company, debt included. Dividing EV by EBITDA (earnings before interest, taxes, depreciation, and amortization) produces a multiple that's less distorted by differences in capital structure (how much debt a company carries) and accounting choices (depreciation methods) than P/E is, which makes it a common tool for comparing companies with meaningfully different balance sheets.
Multiples Only Mean Something Relative to Peers and History
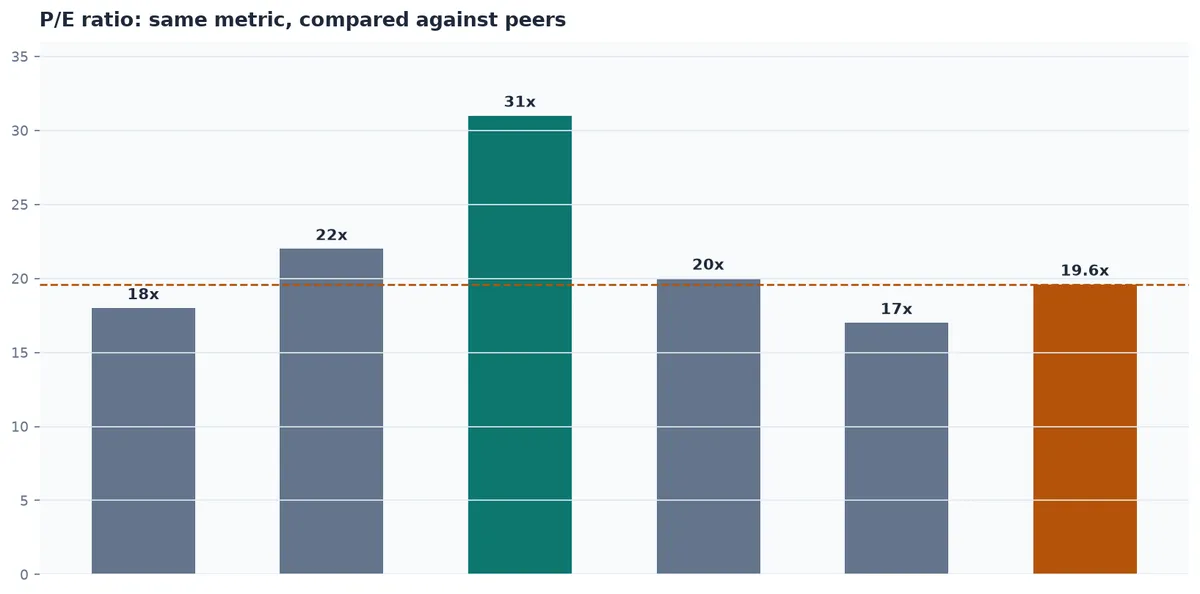
A P/E of 30 is meaningless in isolation — it has to be compared to something. Compared to direct industry peers, it shows whether a company is priced at a premium or discount to similar businesses; compared to the company's own multiple over the past several years, it shows whether the market's willingness to pay for a dollar of its earnings is expanding or contracting. Comparing a software company's P/E to a utility company's P/E, without adjusting for the fact that the two industries have fundamentally different growth rates and capital needs, produces a comparison that looks precise but means very little.
What Multiples Don't Capture
No valuation multiple accounts for qualitative factors like management quality, competitive position, or the durability of a company's advantage — the subject of the next lesson. A statistically cheap multiple on a business with a deteriorating competitive position is a value trap — a stock that looks statistically cheap but keeps getting cheaper because the business itself is weakening — not a bargain, which is exactly why valuation is covered as one input among several rather than a standalone verdict.